-
Monday - Friday 08:00 to 17:00
Can You Buy Property With Your Super in Australia?
Can You Buy Property With Your Super in Australia?
Table of Contents
- Can You Buy Property With Your Super: The Short Answer
- How SMSF Property Loans Work
- Who Can Buy Property Through Super
- Residential vs Commercial SMSF Property
- Costs, Deposits and Borrowing Limits
- The Rules You Must Not Break
- Steps to Buy Property With Your Super
- SMSF Property and Tax
- Is an SMSF Worth It for You?
- Case Study: A Couple Who Bought Their Business Premises
- Frequently Asked Questions
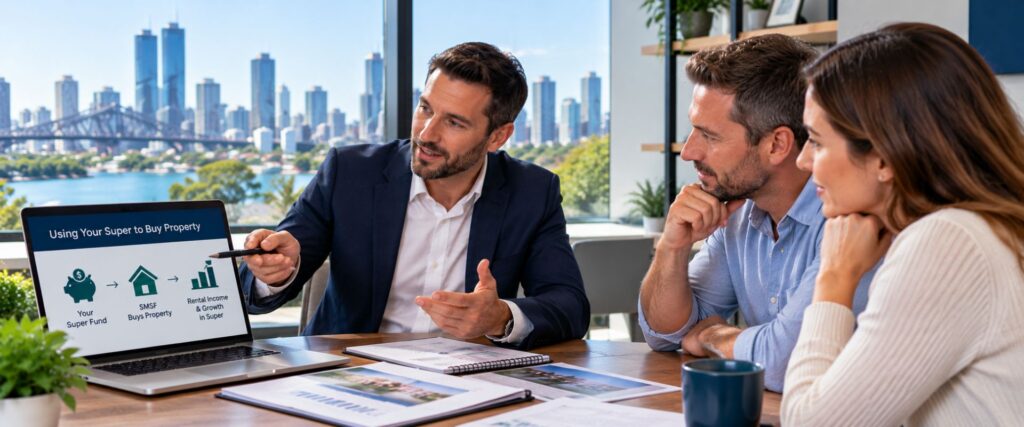
Can you buy property with your super in Australia? Yes, through a self-managed super fund, and it is one of the more powerful ways to grow your retirement savings with property.
It is not as simple as buying in your own name, though. Below we explain the rules, how the loans work, who it suits, the costs, and the traps that can land you in trouble with the regulator.
Can You Buy Property With Your Super: The Short Answer
Yes. You can buy property with your super if you set up a self-managed super fund, or SMSF, and the fund buys the property rather than you personally.
The property is owned by the fund, the rent goes to the fund, and the growth stays inside super until retirement. You cannot live in it or rent it to family if it is residential.
So the real question is not can you buy property with your super, but whether an SMSF suits your balance, your goals and your appetite for admin.
How SMSF Property Loans Work
If the fund does not have enough cash to buy outright, it can borrow using a limited recourse borrowing arrangement, or LRBA. This keeps the loan separate from the fund’s other assets.
Under an LRBA, the lender can only claim the property if the loan defaults, not the rest of your super. That protects your other retirement savings.
Not every lender offers SMSF loans, and terms are stricter than a normal mortgage. A specialist broker knows which lenders are active and competitive.
Who Can Buy Property Through Super
You generally need a reasonable super balance to make an SMSF worthwhile, because setup and running costs eat into small balances.
You also need to be comfortable acting as a trustee, which carries legal responsibilities and annual compliance, including an audit.
It suits people who want direct control of their retirement investments and have the balance, often across a couple, to buy a quality property.
Residential vs Commercial SMSF Property
Your SMSF can buy residential or commercial property, but the rules differ in an important way.
Residential property cannot be lived in or rented by you or your relatives. It must be a genuine investment at arm’s length.
Commercial property is more flexible. Your own business can rent its premises from your SMSF, as long as the rent is at market rate and paid on time. Many business owners use this strategy.
Costs, Deposits and Borrowing Limits
SMSF loans usually need a larger deposit than standard loans, often around 20 to 30 per cent of the property value, plus cash buffers the lender wants to see.
There are setup costs for the fund and the borrowing structure, plus ongoing accounting, audit and compliance fees each year.
The fund also needs enough liquidity to cover repayments, insurance and expenses, so you cannot tip every dollar into the deposit.
The Rules You Must Not Break
The sole purpose test is the big one. The investment must be for retirement benefit only, not for any present-day personal use.
You cannot buy a holiday house to use, buy from or rent to relatives, or improve the property with borrowed money in ways the rules prohibit.
Breaches can be expensive and put your fund’s concessional tax status at risk. For the detail, see the ATO SMSF guidance.
Steps to Buy Property With Your Super
First, get advice on whether an SMSF suits your situation, from a licensed adviser and accountant. This is not a decision to rush.
Next, establish the fund and the borrowing structure correctly, because fixing mistakes later is costly.
Then get your SMSF loan pre-approved so you know your budget, and find a compliant property. An SMSF mortgage broker in Brisbane arranges the finance side.
Finally, settle, lease the property at market rent, and keep clean records for your annual audit.
SMSF Property and Tax
One reason people buy property through super is the tax treatment inside the fund.
Rental income earned by the SMSF is taxed at the concessional super rate, which is lower than most personal income tax rates.
Capital gains on a property held longer than a year also receive a discount inside the fund.
In the pension phase, eligible funds can pay little or no tax on income and gains, which is a powerful long-term benefit.
Tax rules are detailed and change over time, so always confirm the current treatment with your accountant before you rely on it.
Is an SMSF Worth It for You?
An SMSF is not for everyone. The benefits only outweigh the costs above a certain balance.
Setup, accounting, audit and advice fees are largely fixed, so they hurt a small fund far more than a large one.
You also take on real trustee responsibilities and compliance obligations each year.
If you have a healthy balance, often stronger across a couple, and want direct control, it can be very worthwhile.
A quick chat with an adviser and a broker tells you whether the numbers stack up for your situation.
Case Study: A Couple Who Bought Their Business Premises
Sam and Lisa ran a growing trades business in Brisbane and were tired of paying rent to a landlord. They had a combined super balance that made an SMSF viable.
We helped arrange an SMSF loan so their fund bought the commercial unit their business operates from. The business now pays market rent to their own fund.
The rent builds their retirement savings instead of a landlord’s, the property sits inside the concessional super environment, and they control their own premises for the long term.
Frequently Asked Questions
No. Residential property owned by your SMSF cannot be lived in or rented by you or your relatives. It must be a genuine arm’s length investment.
Yes, for commercial property, as long as the rent is at market rate and paid on time. This is a popular strategy for business owners.
Usually more than a standard loan, often around 20 to 30 per cent, plus cash buffers the lender and the fund need to hold.
It carries compliance and liquidity risks, and property is a single large asset. Good advice and a sound structure manage most of the risk.
No. Only some lenders offer them and terms vary widely. A broker knows which lenders are active and competitive right now.
Yes. We arrange the finance and compare SMSF lenders, working alongside your accountant and adviser who handle the fund and tax side.
Conclusion
So, can you buy property with your super? Yes, through a well-structured SMSF, and it can be a smart way to build retirement wealth, especially for business owners buying their own premises.
The structure and compliance matter, so get it right from the start. Talk to an SMSF mortgage broker in Brisbane for a free review of your finance options.
Reviewed by Philip Jenkins, principal broker at A Loan For You (ABN 56 125 306 121, Credit Representative 365865), helping Brisbane borrowers since 2006.
This article is general information only and not personal financial or credit advice. Consider your own situation and speak to a licensed mortgage broker before acting.
A Loan For you is a Local Brisbane mortgage and finance brokers, comparing 50+ lenders to find the right loan for you, with no fees for our service.
Contact Info:
-
Address: 20 Arundel St, Brighton QLD 4017
-
-
Phone: 0405 409 922