-
Monday - Friday 08:00 to 17:00
Car Loan vs Dealer Finance: Which Saves You More?
Car Loan vs Dealer Finance: Which Saves You More?
Table of Contents
- Car Loan vs Dealer Finance: The Core Difference
- How Dealer Finance Really Works
- How a Broker Car Loan Works
- Comparing the True Cost
- When Dealer Finance Can Make Sense
- Fees and Traps to Watch
- How to Get the Cheapest Car Loan
- New vs Used Car Finance
- Novated Lease vs Car Loan
- Case Study: A Buyer Who Saved Thousands on a New SUV
- Frequently Asked Questions
The car loan vs dealer finance decision can cost or save you thousands over the life of the loan, yet most buyers sign up for dealer finance on the spot without comparing.
Below we break down how each option really works, how to compare the true cost, when dealer finance makes sense, and how to get the cheapest car loan in Brisbane.
Car Loan vs Dealer Finance: The Core Difference
In the car loan vs dealer finance choice, a car loan is arranged independently through a lender or broker, while dealer finance is arranged by the dealership at the point of sale.
Dealer finance is convenient because it is right there, but convenience often comes at a price in the rate and the fees.
An independent car loan lets you compare lenders and walk in as a cash buyer, which strengthens your negotiating position on the car itself.
How Dealer Finance Really Works
Dealers usually act as a middleman for a finance company and can add a margin to the interest rate, which is how they earn from the loan.
The advertised low rate often applies only to selected models or buyers, and may come with conditions or a balloon payment at the end.
It is quick and easy, but easy is not the same as cheap, and the total cost can be higher than it first appears.
How a Broker Car Loan Works
A broker compares lenders across the market and matches you to a competitive rate based on your situation, not just the one finance company a dealer uses.
You get pre-approved before you shop, so you know your budget and can negotiate the car price separately from the finance.
This separation is powerful. Dealers make money on both the car and the finance, so controlling the finance yourself removes one of their levers.
Comparing the True Cost
Never compare on the monthly repayment alone. A lower monthly figure can hide a longer term or a balloon that costs more overall.
Compare the comparison rate, which includes most fees, and the total amount repaid over the full term.
Also check for ongoing fees, early exit penalties and whether the rate is fixed. These details often matter more than the headline number.
When Dealer Finance Can Make Sense
Sometimes a manufacturer runs a genuine low-rate or zero-rate campaign on a specific model, which can beat a standard car loan.
If you qualify and the car is one you wanted anyway, that offer can be worthwhile.
The trick is to still get an independent quote first, so you can tell whether the dealer offer is truly cheaper or just marketed that way.
Fees and Traps to Watch
Watch for balloon or residual payments that leave a large sum owing at the end of the term.
Watch for add-ons bundled into the finance, such as overpriced insurance or warranties that inflate the loan.
And watch for long terms that lower the monthly payment but cost far more in interest. See ASIC Moneysmart for a car loan checklist.
How to Get the Cheapest Car Loan
Get pre-approved through a broker first, so you know your rate and budget before you set foot in a dealership.
Keep the loan term as short as you can comfortably afford, since shorter terms cost far less interest.
Then negotiate the car price as a cash buyer. A car loan broker in Brisbane lines up the finance so you only haggle on the car.
New vs Used Car Finance
Finance for a new car is usually cheaper than for an old one, because a newer vehicle is better security for the lender.
As a car ages, lenders may charge a higher rate or limit the loan term, since the asset is worth less.
Very old cars can be hard to finance with a secured car loan at all, and a personal loan may be the option instead.
Whatever the age, the car secures the loan, so keeping it insured protects both you and the lender.
A broker knows which lenders are comfortable with older vehicles and private sales, which banks often avoid.
Novated Lease vs Car Loan
If you are an employee, a novated lease lets you pay for a car and its running costs from your pre-tax salary.
For some buyers this beats a standard car loan, because it can reduce taxable income.
It depends on your salary, the car, and whether your employer offers salary packaging.
A car loan is simpler, has no tie to your employer, and suits the self-employed and anyone who values flexibility.
Comparing both for your situation is worthwhile, and a broker can run the numbers side by side.
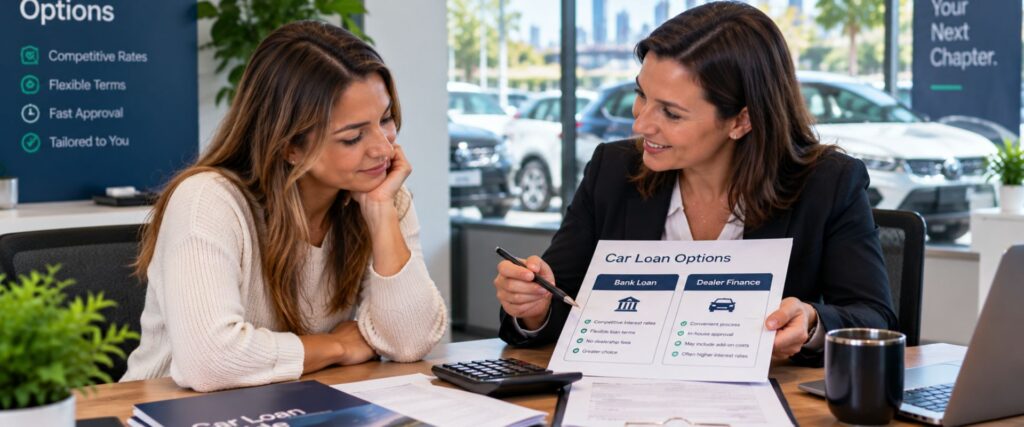
Case Study: A Buyer Who Saved Thousands on a New SUV
Ben was about to sign dealer finance on a new SUV at a rate that sounded fine until he looked closer. The term was long and there was a balloon at the end.
He paused and came to us. We pre-approved him at a sharper rate over a shorter term with no balloon, and he returned to the dealer as a cash buyer.
He negotiated a better price on the car and saved several thousand dollars across the life of the loan, simply by comparing before signing.
Frequently Asked Questions
Often yes, because dealers can add a margin to the rate and bundle in extras. Always compare an independent quote before signing.
A balloon is a large lump sum owing at the end of the term. It lowers monthly repayments but increases the total cost and leaves a bill to settle later.
Usually, because a broker compares many lenders rather than one finance company. Occasionally a genuine manufacturer campaign wins, which is why you compare.
Yes. Pre-approval tells you your real budget and lets you negotiate the car price as a cash buyer, separate from the finance.
Yes. A shorter term means less interest overall, even though the monthly repayment is higher. Only go as short as you can comfortably afford.
Often yes. If you are stuck in a high-rate dealer loan, a broker may be able to refinance you to a cheaper rate and save you money.
Conclusion
In the car loan vs dealer finance contest, an independent car loan usually wins on cost and gives you a stronger hand at the dealership. Dealer finance only wins on a genuine manufacturer deal.
Before you sign anything, get a quick quote from a car loan broker in Brisbane. It is free and could save you thousands.
Reviewed by Philip Jenkins, principal broker at A Loan For You (ABN 56 125 306 121, Credit Representative 365865), helping Brisbane borrowers since 2006.
This article is general information only and not personal financial or credit advice. Consider your own situation and speak to a licensed mortgage broker before acting.
A Loan For you is a Local Brisbane mortgage and finance brokers, comparing 50+ lenders to find the right loan for you, with no fees for our service.
Contact Info:
-
Address: 20 Arundel St, Brighton QLD 4017
-
-
Phone: 0405 409 922